The Buy-to-Let Reality: The True Cost of Property vs. Equities
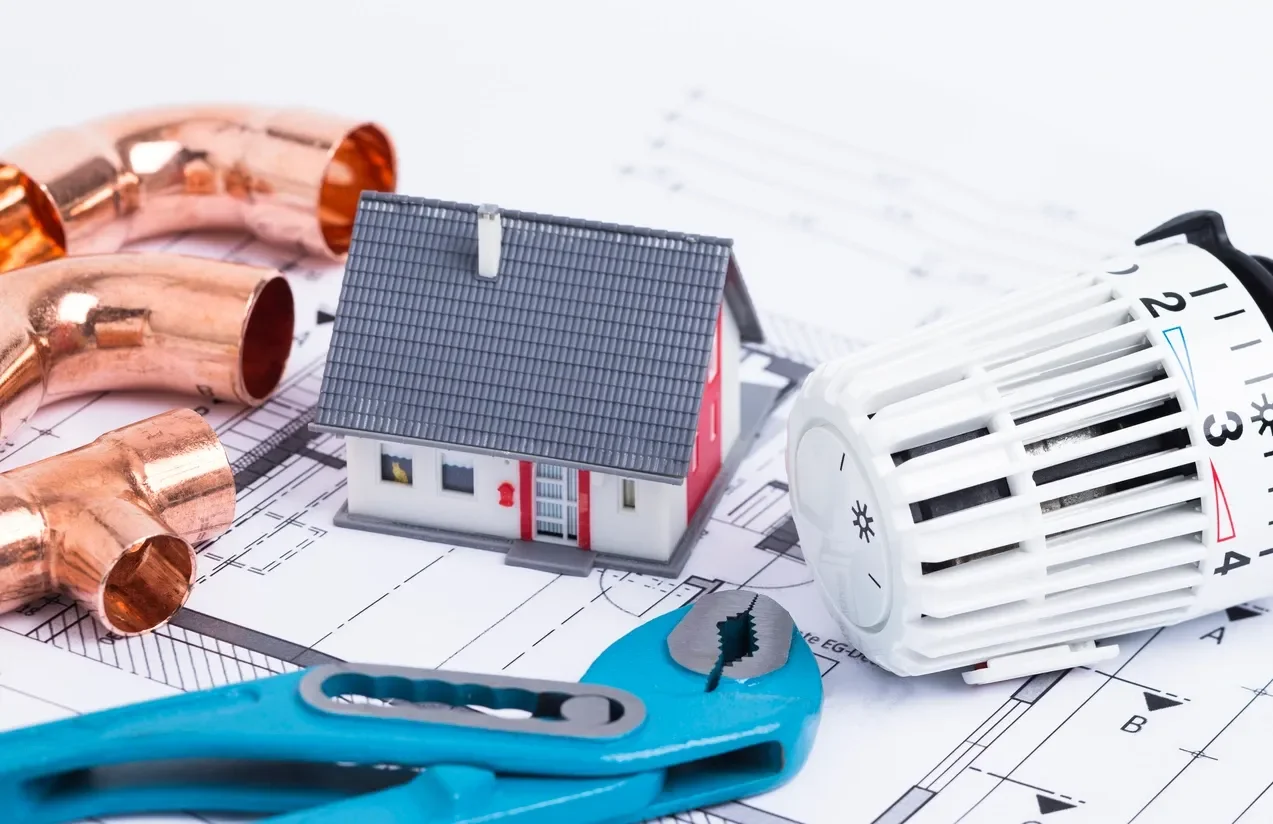
In the UK, we have a cultural obsession with bricks and mortar. When successful professionals start building wealth for their retirement, the conversation almost inevitably turns to investment property. The allure is entirely understandable; you can see it, touch it, and understand exactly how it generates rent.
Because of this tangibility, property is frequently marketed as the ultimate source of "passive income." But after two decades of advising clients on both their investment portfolios and their property finance, I can assure you that managing real estate is rarely passive.
When you look beyond the surface-level price tag, the true cost of owning physical assets extends far beyond the initial deposit.
The High-Hassle Game of Property
When forecasting returns on a Buy-to-Let property, investors often look at the rental yield and the mortgage rate, and assume the rest is pure profit. This is a dangerous oversimplification.
The modern UK property market carries an extensive list of ongoing financial demands. Beyond the heavy upfront sting of Stamp Duty, landlords must account for maintenance, void periods, letting agent fees, rising insurance premiums, and the looming costs of mandatory EPC upgrades.
However, the most expensive hidden fee is the "hassle factor." Property investment requires your time, your energy, and your attention. From midnight calls about a broken boiler to navigating complex changes in tenant legislation, property is effectively a part-time business.
Furthermore, property is highly illiquid. If you need £50,000 to fund a child's university education or a sudden life event, you cannot simply sell the kitchen of your investment property. It is a one-and-done deal, which makes strategic Capital Gains Tax planning incredibly rigid.
The Elegance of Equities
Contrast this with the realities of owning a globally diversified equity portfolio.
Building a robust portfolio of great global companies demands careful, informed decision-making upfront. But in terms of ongoing effort, it asks almost nothing of you. Counterintuitively, the less you do, the more likely you are to succeed.
Day-to-day, the companies you own are run by professional boards, while your capital is actively monitored by experienced fund managers and custodians. You do not have to fix their plumbing or chase them for the rent. You simply capture the long-term growth of human innovation and commerce. You also have total liquidity; you can draw down exactly what you need, exactly when you need it, in a highly tax-efficient manner.
The only true "cost" of an equity portfolio is the emotional fortitude required to endure temporary market fluctuations. But while the anxiety of a temporary market dip fades quickly, the long-term compounding growth remains.
Optimising Your Time and Wealth
This is not to say that property is a bad investment. For the right investor, with the right financing and the right temperament, expanding a property portfolio is a powerful wealth-building tool.
However, genuine financial planning is about more than just allocating capital. It is about optimising your time, energy, and stress levels as you approach retirement.
Before committing to an asset class, it pays to have an objective conversation about what it truly means to own it. When you understand the full spectrum of costs—both financial and emotional—you can build a strategy that doesn't just look good on a spreadsheet, but actually enhances your quality of life.