
protection adviser
Protection Built Around What You'd Actually LoseIndependent advice on the cover that protects your family, your income, or your business if life doesn't go to plan.
Independent, and On Your Side
The right protection is the foundation everything else rests on. Get it wrong and a sound financial plan can unravel the moment life doesn't go to plan. As an independent protection adviser in London, my job is to work out what you actually need, no more and no less, and make sure the cover pays out cleanly when it's called on.
We're not tied to any insurer or product provider. As an independent protection adviser in London, we recommend the policy that genuinely fits your circumstances, not whichever one comes with the best commission. We'll explain the terms clearly, so you know exactly what you're covered for and can choose with confidence.
Types of CoverCover for Your Life, and Your Business
Protection isn't one-size-fits-all. Whether you're protecting your family or your business, here's what we advise on:
Personal Cover
Life cover: protecting your family or your mortgage if the worst happens
Critical illness cover: a lump sum if you're diagnosed with a serious condition
Income protection: a replacement income if illness or injury stops you working
Whole of life cover: permanent cover, often used in estate and inheritance planning
Business Cover
Relevant life cover: tax-efficient life cover arranged through your company
Executive income protection: company-funded income protection for directors and key employees
Key person cover: protecting a business against the loss of someone critical to it
Shareholder protection: surviving partners can keep control of the business while paying the deceased partner's family a fair value for their share.
Your Financial Planner
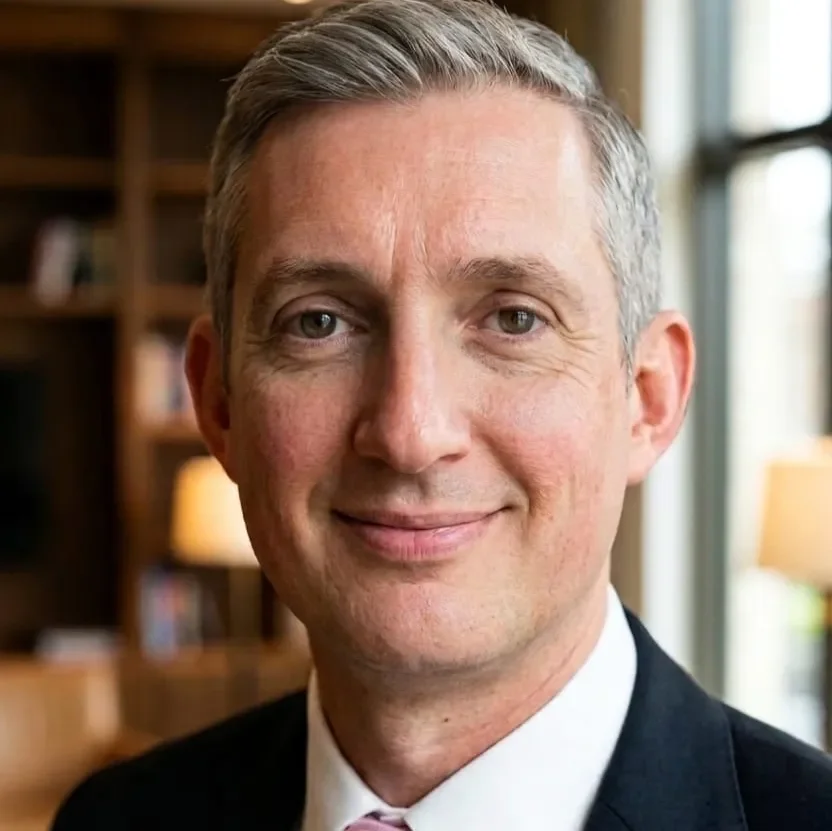
Sam Pemberton
Founder, Candor Rubra Financial Ltd
Protection at Every StageWhat You Need to Protect Changes as Your Life Does
Protection isn't a one-off decision made in your twenties and forgotten about. What's actually at risk, and what you stand to lose, shifts significantly as your life and responsibilities change. As your life insurance adviser, we can help you choose the right protection, for the right time.
While You're Building Wealth
This is usually the stage with the most to lose and the least in reserve. A mortgage, a young family, a business still finding its feet, all of it depends on your income continuing to arrive. Cover at this stage tends to matter more than people expect, and gets put off more than it should.
While You're Living Off Your Retirement Pot
The risks change rather than disappear. Later-life cover, and making sure a partner isn't left in a difficult financial position, becomes the priority instead of income replacement.
While You're Passing On Your Legacy
At this stage, whole of life cover does a different job. It's no longer about replacing income, but about making sure the estate you've built passes on intact, rather than being eroded by an Inheritance Tax bill or forced sales at the worst possible time.
Leaving protection unaddressed at any of these stages carries a real cost, even though it rarely feels urgent until it is.
A family without adequate life or income cover can face a sudden, severe financial gap at the worst possible time. A business without key person cover can struggle to survive the loss of the person it depended on most. And an estate without the right cover in place can lose a significant share of its value to tax that could have been planned for. None of this shows up as a problem, until the day it does.
Our processA Clear Process, Start to Finish
Protection can feel like an afterthought until you actually need it, which is exactly when it needs to work. As a life insurance adviser, we keep the process straightforward and keep you informed at every stage.
Book an initial chat
A relaxed, zero-obligation conversation to talk through your circumstances and what you're trying to protect.
01 Assessment
We work out what cover you actually need, and what you don't.
02 Recommendations
You get a clear comparison of policies, explained in plain English.
03 Ongoing support
We're on hand if your circumstances change or you ever need to make a claim.
04 Get in contactLet's Make Sure You're Actually Covered
Book a free, no-obligation chat with a life insurance adviser in London who'll tell you exactly what you need, and what you don't.
-
It's a good start, but death-in-service tends to get absorbed by the sudden drop in income rather than clearing the mortgage and other liabilities your family is left with. It's also usually a multiple of salary rather than what they'd actually need, it's tied to your employer, and it disappears the moment you change jobs. Worth checking what you'd really be left with before assuming it's covered.
-
It can feel that way right up until it's needed, at which point it's the only thing that matters. The real question isn't whether you can afford the premium, it's whether your family or business could absorb the loss of your income without it.
-
Most claims aren't the result of carelessness, they're the result of things nobody plans for: illness, injury, or worse, arriving without warning. Cover is cheaper and easier to arrange while you're healthy, which is exactly why it's worth sorting now rather than waiting for a reason to need it.