
wealth management firm london
Wealth Management, Built Around Your LifeIndependent wealth management that starts with your goals, not a list of products we're trying to sell you.
What are you building towards, what worries you, and what does financial security actually look like for you?
Wealth management should start with your life, not assumptions.
Only once that's clear does it make sense to talk about investments, tax and structure. As an independent wealth management firm in London, that's exactly the order we work in.
As we're an independent wealth management firm in London, we're not restricted to one company's funds or platforms. We build your plan using platforms and funds chosen on their merits, drawing on highly-rated platforms and well-regarded, strongly performing funds, then match them to your goals and your attitude to investment risk (through a psychometric test). Quality is the starting point. Fit to your circumstances is what decides the recommendation.
Fees are transparent and agreed upfront. No hidden commissions, no products we're incentivised to push. That's the whole idea behind the firm.
What's includedA Plan Built on Your Life, Not a Template
Good wealth management isn't a product, it's a plan that reflects where you are and where you want to get to. Here's what that actually covers:
Total Financial Clarity
A complete, honest view of your assets, income, liabilities and goals, paired with an investment strategy matched to your risk appetite.
A Plan That Evolves
Regular reviews keep your strategy aligned with your life, because a plan that's never revisited is just a document.
Tax Efficiency
Making full use of ISAs, pensions and allowances, so more of your money stays yours instead of going to tax unnecessarily.
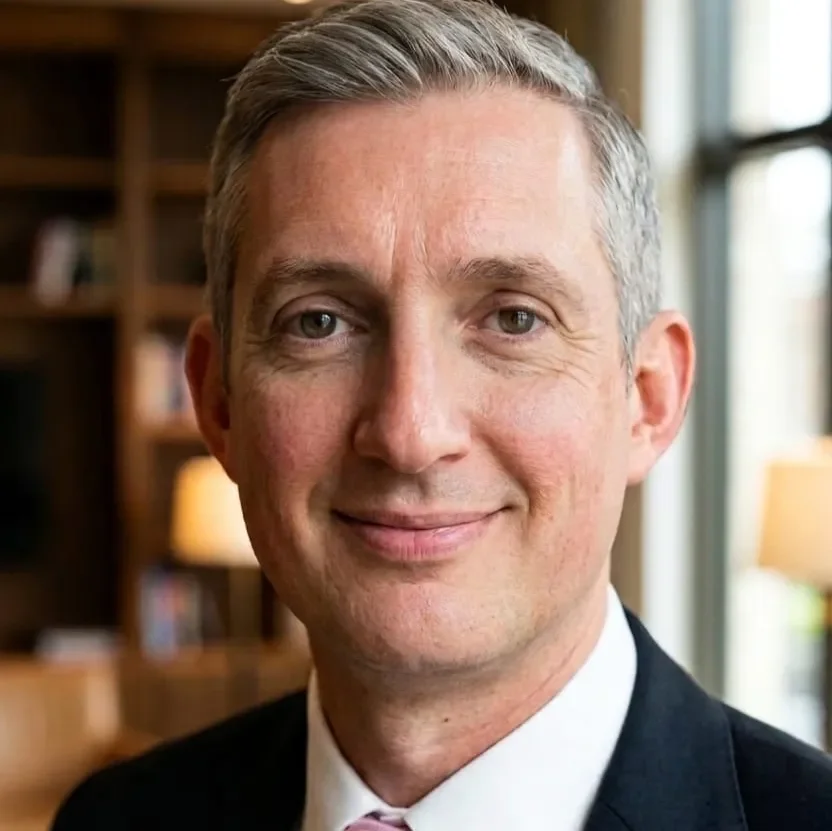
Your Financial Planner
Sam Pemberton
Founder, Candor Rubra Financial Ltd
Your Needs Change. Your Plan Should TooWealth Management at Every Stage
Wealth management doesn't look the same at 35 as it does at 65. The strategy that's right for building wealth is rarely the one that's right for living off it, and neither is the one that's right for passing it on. Treating all three the same way is one of the most common, and costly, mistakes people make.
While You're Building Your Wealth
Your money should be working as hard as you are, and it's often the case that a scattering of decisions made over the years hasn't actually added up to a coherent strategy. We bring it together into one plan matched to your goals and risk appetite.
While You're Living Off Your Retirement Pot
The instinct to play it safe can quietly work against you. Withdrawing without a strategy, leaving money sitting in low-growth or high cost accounts as returns fail to keep pace, can erode a retirement fund faster than planned.
While You're Passing On Your Legacy
Wealth built without a structure for what happens next often ends up costing more to pass on than it needed to. A plan built with the next generation in mind changes that.
Our processA Clear Process To Building Wealth on Your Terms
Wealth management can feel abstract if you're not sure what it actually involves day to day. We keep it simple and keep you informed at every stage, from the first conversation about what matters to you, through to a plan that's reviewed and adjusted as life changes.
Book an initial chat
A relaxed, zero-obligation conversation to understand where you are now and what you want to achieve.
01 Assessment
We map out your current assets, income, liabilities and risk appetite.
02 Recommendations
You get a tailored strategy plan, covering investments, tax and structure, explained clearly.
03 Ongoing reviews & support
We revisit the plan regularly, so it keeps working as your circumstances change.
04 Get in contactLet's Build a Plan Around Your Life
Book a free, no-obligation chat with a wealth management firm in London that starts with your goals, not a product list.
-
It's part of it, but wealth management is about how those pieces work together, alongside tax efficiency, investment strategy and regular review. Having accounts isn't the same as having a plan for them.
-
No. What matters more is having clear goals and wanting a deliberate strategy to reach them, not a minimum amount of assets. Plenty of people benefit from getting organised well before they'd consider themselves "wealthy."
-
You can, and for some people that's genuinely fine. But self-directed investing rarely accounts for tax efficiency, risk matched properly to your goals, or a plan that adjusts as your life changes. The value of advice tends to show up over years, not in any single decision.
The value of investments and pensions, and any income from them can fall as well as rise. You may not get back the full amount invested.
Past performance is used as a guide only; it is no guarantee of future performance.
Levels and bases of, and reliefs from, taxation are subject to change, and their value will depend upon personal circumstances. Taxation and pension legislation may change in the future.
Drawdown pension plans (unsecured income) are complex and are not suitable for everyone. Pension decisions can affect your income for the rest of your life (and that of any partner and other dependants). Where benefits are accessed on a flexible basis, these are not fixed or safeguarded for life. If security of income is important to you then you should consider purchasing an annuity or taking a scheme pension to provide a secured level of income.
The Financial Conduct Authority (FCA) does not regulate Inheritance Tax Planning or Trust Advice.